
Financial leaders have spent a decade trying to fit cryptocurrency into familiar boxes: Is it a currency? A commodity? A security? This is the wrong framework entirely. Crypto is not an asset to be categorized; it is a chaotic, self-organizing ecosystem. Like a digital rainforest, it is teeming with new life, unpredictable growth, and immense potential energy. Viewing it through the lens of a managed portfolio is like trying to plant a garden in the Amazon. Instead of trying to control it, leading firms are learning to participate within it. They are finding their niche, forming symbiotic partnerships, and adapting to its rules. Our Vivaldi crypto analysis shows that success isn’t about domestication, but about integration. The challenge is to find your place in the food chain.
With the acceleration of digital currencies, what’s the right next step for financial institutions? Since their launch in 2009, cryptocurrencies have experienced losses of more than 50% six times with no signs of stabilizing in the near term given the recent Fed moves and continued skepticism among some traditional players and key opinion leaders. For instance, Jamie Dimon, the CEO of JP Morgan Chase has taken to calling them “crypto-tokens,” rather than currency, and has stated that he views bitcoin as “worthless.” At the Berkshire Hathaway annual shareholders meeting in April, Warren Buffett said of bitcoin: “Whether it goes up or down in the next year, or five or 10 years, I don’t know. But the one thing I’m pretty sure of is that it doesn’t produce anything.” He explained further, “Assets, to have value, have to deliver something to somebody.” But this perspective is not shared by all. Many large traditional financial players are beginning to test the waters to find the best way to participate in this new technology. They’re exploring how to leverage existing products and form partnerships to solidify their strategy around crypto. In the first fiscal quarter of 2022, customers made $2.5 billion in payments using crypto-linked cards from Visa — a 150% increase from Visa’s crypto activity during all of 2021. Visa also expanded their offerings to include a crypto advisory practice for clients seeking additional services. Rising consumer interest led Mastercard to partner with leading digital currency companies across Asia-Pacific to launch the region’s first crypto-linked payment card, and last year, Mastercard partnered with Bakkt, Gemini, and Mintable, among others, to let banks and merchants into its network of crypto-related services. Finally, American Express has jumped in and recently announced the Abra Crypto Card, the first crypto rewards credit card on the American Express network that will transact in U.S. dollars and offer crypto back on any purchase category and amount. Although this new evolution has been a roller coaster ride so far, the expansion of the cryptocurrency ecosystem is only going to continue, shaped by increasing consumer demand. In response, financial services companies and emerging fintechs have shifted from proceeding with caution to evolving their offerings in order to play more of a leading role in crypto. PayPal is a great example, as they’ve embarked on a multi-year journey to constantly evolve their strategy to deliver on the desired customer experience. They’ve charted a course to allow customers to trade crypto, make purchases from over 29 million merchants, and share purchases socially with Venmo. 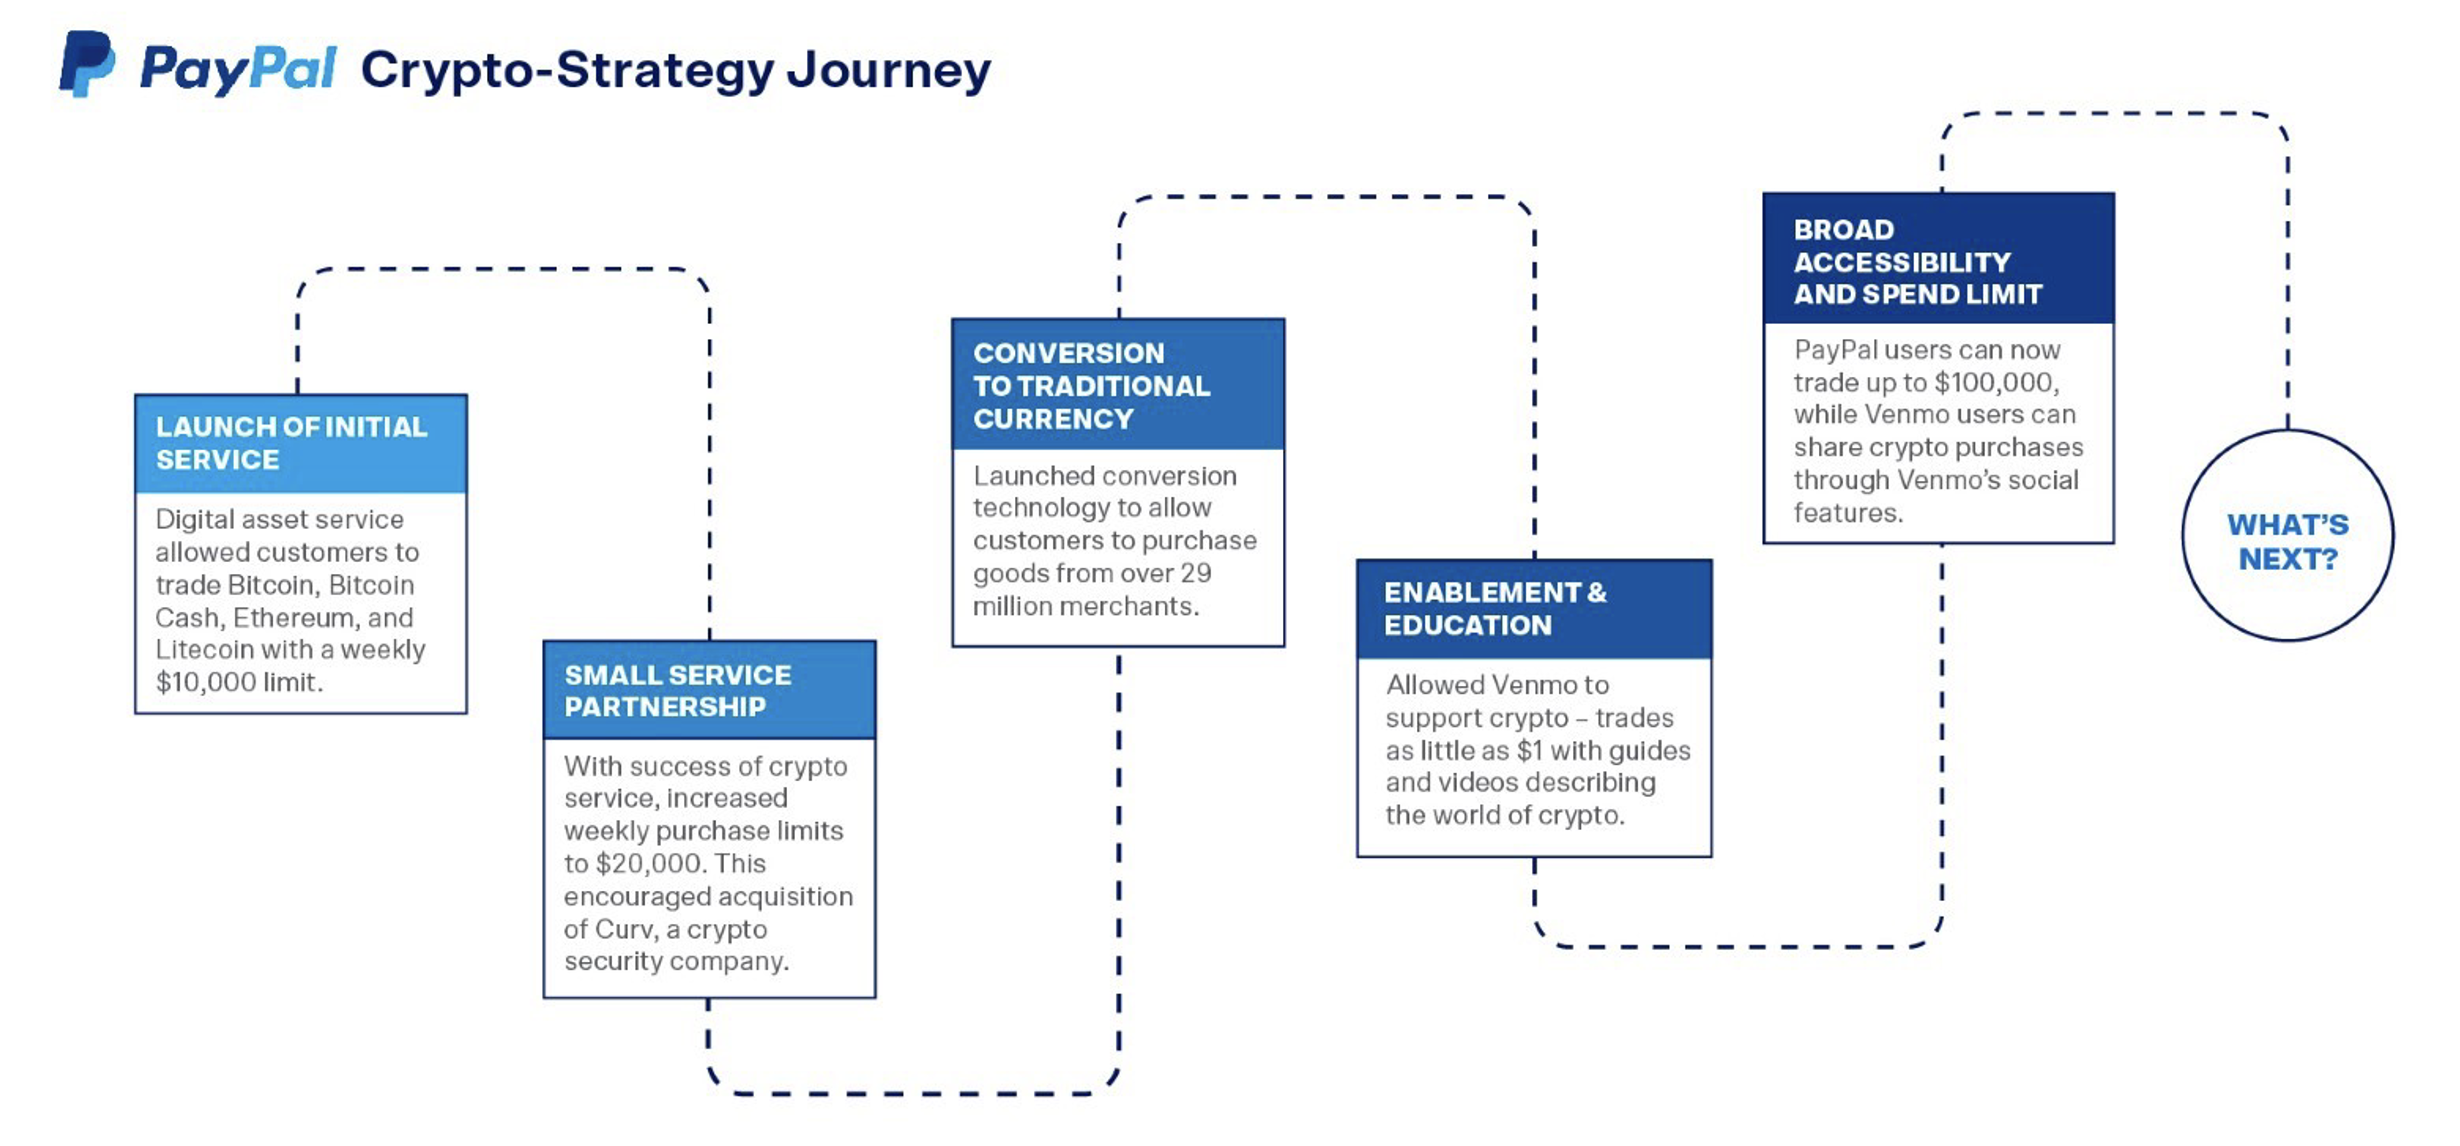 In short, like PayPal, the businesses and brands who can anticipate what consumers will want and identify how the technology, partnerships, and benefits of crypto can deliver on those expectations, will win. As with any new technology adoption, it will require continuous listening to the consumer, a focused customer-first mindset, and the ability to test and learn so that consumers can help shape your crypto strategy. It isn’t a question of should you participate in the cryptocurrency space, but rather, what should be your role in the crypto ecosystem. Larry Lucas is a Senior Partner at Vivaldi who specializes in business and brand transformation and driving change within organizations. Ben Kuenzle is a Partner at Vivaldi who specializes in growth and innovation, brand/marketing strategy, and product marketing.
Frequently Asked Questions
My leadership thinks crypto is just a volatile, speculative asset. How do I change that conversation? The key is to reframe the discussion from investment to infrastructure. The debate over whether Bitcoin is “worthless” or not misses the point. Millions of consumers are already using crypto-linked cards for everyday payments, as the Visa and Mastercard examples show. The conversation shouldn’t be about your company’s balance sheet, but about your role in a new financial system your customers are actively exploring. Focus on the utility and the emerging consumer behaviors, not just the price charts.
What does it mean to “find our role” in the crypto ecosystem? Can you give an example? Finding your role means identifying where your company’s core strengths can add unique value within this new landscape. It’s not about becoming a crypto exchange overnight. For instance, if your brand is built on trust and security, your role might be to offer secure custody solutions. If you excel at customer rewards, you could follow American Express’s lead and develop a crypto-rewards program. Your role should be an authentic extension of what your brand already promises customers, simply applied to a new technology.
We’re not a fintech company like PayPal. How can a more traditional financial institution start? You don’t need to build everything from scratch. The most effective first step is often forming strategic partnerships. Look at how Mastercard is working with established digital currency companies to bring services to its network. A practical start is to create a small, dedicated team to explore these partnerships and listen intently to what your most innovative customers are asking for. The goal isn’t a massive, risky launch, but to build internal knowledge and test the waters with a focused, low-risk pilot.
How do we build a strategy around something so unpredictable and constantly changing? You build an adaptive strategy, not a rigid one. Instead of a five-year plan that will be obsolete in six months, focus on establishing guiding principles and a “test and learn” capability. Your strategy should be a framework for making decisions, not a fixed roadmap. The goal is to become agile enough to respond to market shifts and consumer demands as they happen, much like PayPal continuously evolves its offerings based on user feedback and behavior.
Is the goal to replace our current offerings with crypto, or something else? For most established institutions, the goal is integration, not replacement. Think of this as building a bridge, not jumping to a new island. Your customers still operate in the world of traditional finance, but they are increasingly active in the digital ecosystem. The strategic opportunity is to connect these two worlds for them, making it easier and safer to move between them. It’s about adding a powerful new capability to your existing services to meet a clear and growing customer need.
Key Takeaways
- Shift from Asset Management to Ecosystem Participation: The most successful players aren’t trying to control crypto; they’re finding their place within its chaotic, self-organizing system. The strategic question isn’t “what is it?” but “what is our role in it?”
- Let Customer Adoption Guide Your Strategy: Ignore the noise of market speculation and focus on the clear signal from consumer behavior. People are already using crypto-linked cards for everyday payments, proving that the demand for practical applications is real and growing.
- Embrace a Test-and-Learn Approach: Your entry into crypto isn’t a one-time launch; it’s the beginning of a continuous learning cycle. The winning formula is to get in the game, listen intently to consumer feedback, and constantly evolve your offerings based on real-world use.